Buying a home in Ahmedabad from abroad: the NRI checklist
Thousands of Gujarati families abroad buy in Ahmedabad every year, many without flying home. What the rules allow, how the money has to move, and the paperwork that trips people up most often.
By NB Legal & CRM
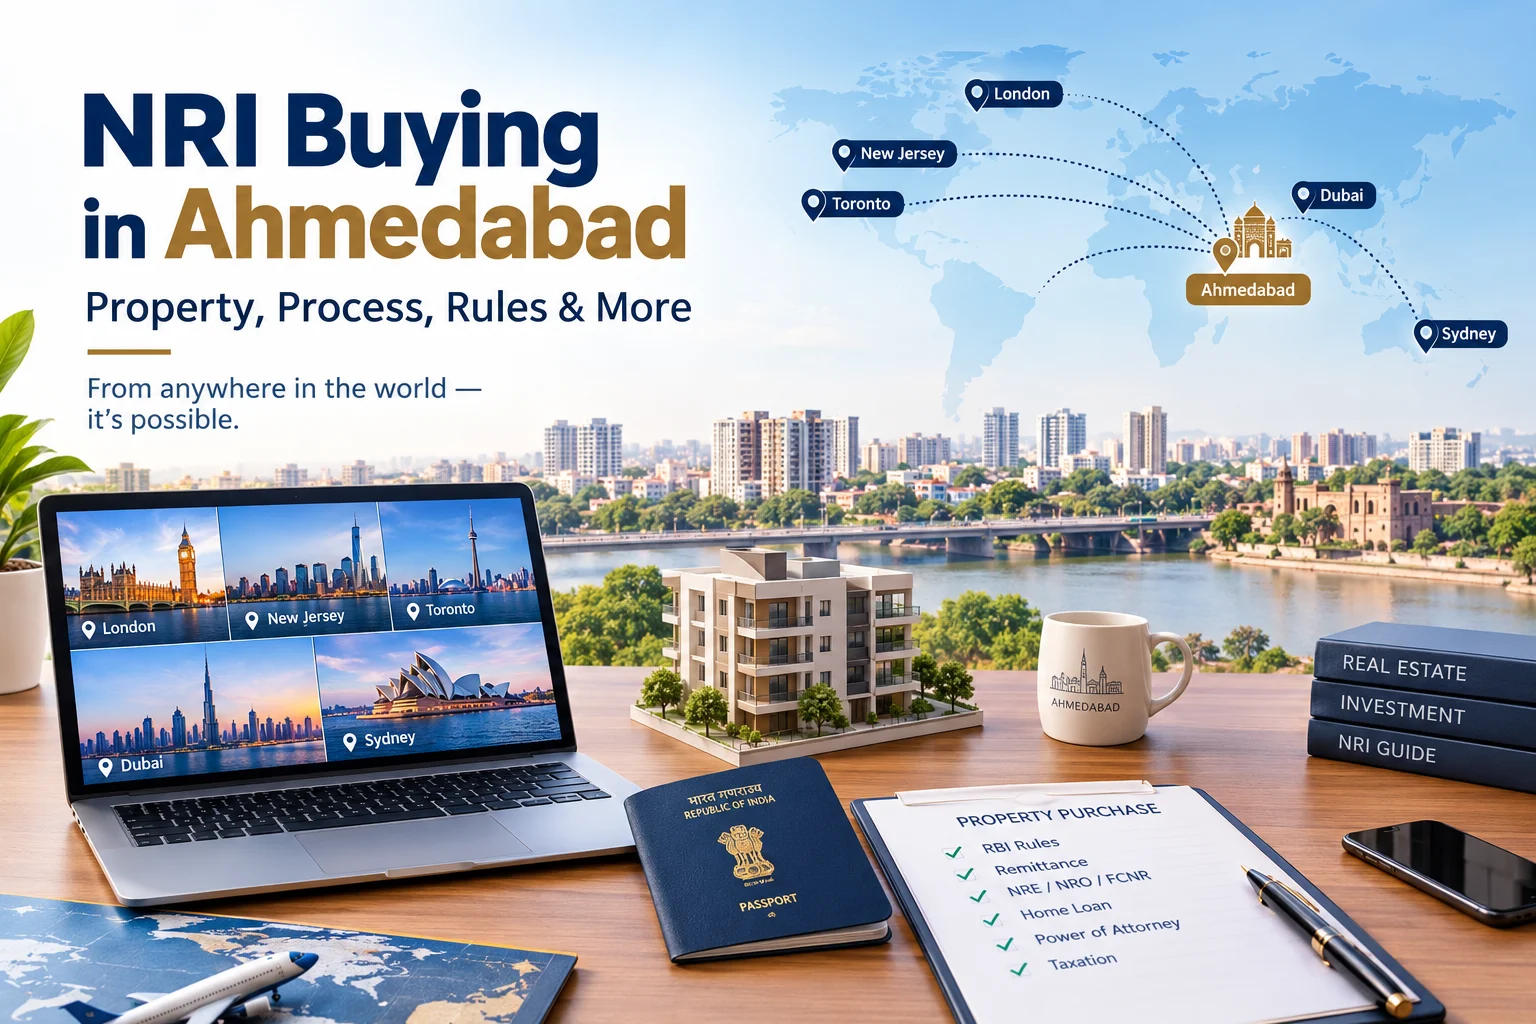
Every week the NB desk takes calls from London, New Jersey, Toronto, Dubai and Sydney. The question is nearly always the same: can I do this from here? For NRI buying in Ahmedabad the answer is nearly always yes, with one trip or none at all, provided the money and the paperwork follow a few rules.
What you are allowed to buy
Under India’s foreign exchange rules, set by the Reserve Bank of India, Non-Resident Indians and Overseas Citizens of India can buy residential and commercial property in India without any special permission from the Reserve Bank. There is no limit on the number of homes.
What you cannot buy is agricultural land, plantation property or a farmhouse, except by inheritance.
How the money has to move
This is where most problems start, and they are easy to avoid.
- Pay through normal banking channels: an inward remittance from abroad, or from your NRE, NRO or FCNR account in India.
- Do not pay in foreign currency notes or travellers’ cheques. Do not pay from a friend’s account.
- Keep every remittance advice. You will need them to repatriate money if you ever sell.
Which account to pay from:
- NRE holds money earned abroad, in rupees. Use it for payments you may want to repatriate later.
- NRO holds income earned in India. Use it to put rent or other Indian income towards the home.
- FCNR holds deposits in foreign currency, for buyers who want to limit currency risk until they pay.
Home loans for NRIs
Most Indian banks and housing finance companies lend to NRIs, usually against proof of overseas income and an employment contract. EMIs are paid from an NRE or NRO account. Tenures and loan-to-value limits vary by lender; our EMI calculator gives a quick sense of the monthly figure.
Power of attorney: the step that trips people up
If you cannot be in Ahmedabad to sign the agreement and register it, a family member can act for you with a power of attorney. Three rules matter:
- Make it specific. A POA for “the purchase and registration of flat no. __ in __ tower” is accepted far more readily than a general one.
- Sign it properly abroad. It must be attested at the Indian embassy or consulate, or apostilled, depending on the country.
- Adjudicate it on arrival. Once in India it must be stamped by the Sub-Registrar within three months.
Tax, briefly
Rental income from the home is taxable in India, and you may be able to claim credit for it abroad under a tax treaty. When you sell, the buyer deducts tax at source at the rates applicable to non-residents. Speak to a chartered accountant in both countries before you commit; it is cheaper than fixing it afterwards.
NRI buying in Ahmedabad without flying
For buyers overseas, a typical NB purchase looks like this: a live video walkthrough of the sample flat and the site, plans and the RERA page shared digitally, a booking by remittance, the agreement signed by your POA holder in Ahmedabad, and progress photographs from the site team every quarter until possession.
NRI Corner. Our NRI Corner has the desk’s hours in your time zone and a call-back form that picks a time that suits both of us.
Most NRI buyers we work with visit once, often for the handover, and some not at all until they move in. The rules are settled and the process is well worn; what makes it smooth is a developer that answers in your time zone and keeps every document in one place.
General information, not legal or tax advice. FEMA and tax rules change; confirm your own case with a qualified advisor.